Nvidia NVDA is facing renewed selling pressure as investors assess whether the artificial intelligence chipmaker’s latest crisis has created a buying opportunity or exposed bigger risks.
Shares closed Wednesday, November 11, at $173.73, up approximately 2.9% during the regular session, before falling more than 8% in extended trading following reports that the company’s board was considering removing chief executive Jensen Huang.
With Nvidia’s valuation falling sharply and its next earnings report scheduled for November 17, investors face a difficult question: is Nvidia still a good buy, or could the stock fall further?
Is Nvidia still a good buy?
Nvidia’s recent decline has made the stock look considerably more attractive on traditional valuation measures, particularly given the company’s exceptional revenue growth and dominant position in AI computing.
However, a lower share price does not necessarily mean the risks have disappeared.
For long-term investors who remain confident in AI infrastructure demand, the sell-off could offer an opportunity to gain exposure at a lower valuation.
For those considering a short-term position, uncertainty surrounding Huang’s future and the upcoming earnings announcement could make waiting for greater clarity a more cautious approach.
Much depends on whether the current disruption affects Nvidia’s underlying business or primarily reflects a loss of investor confidence.
Why is Nvidia stock falling?
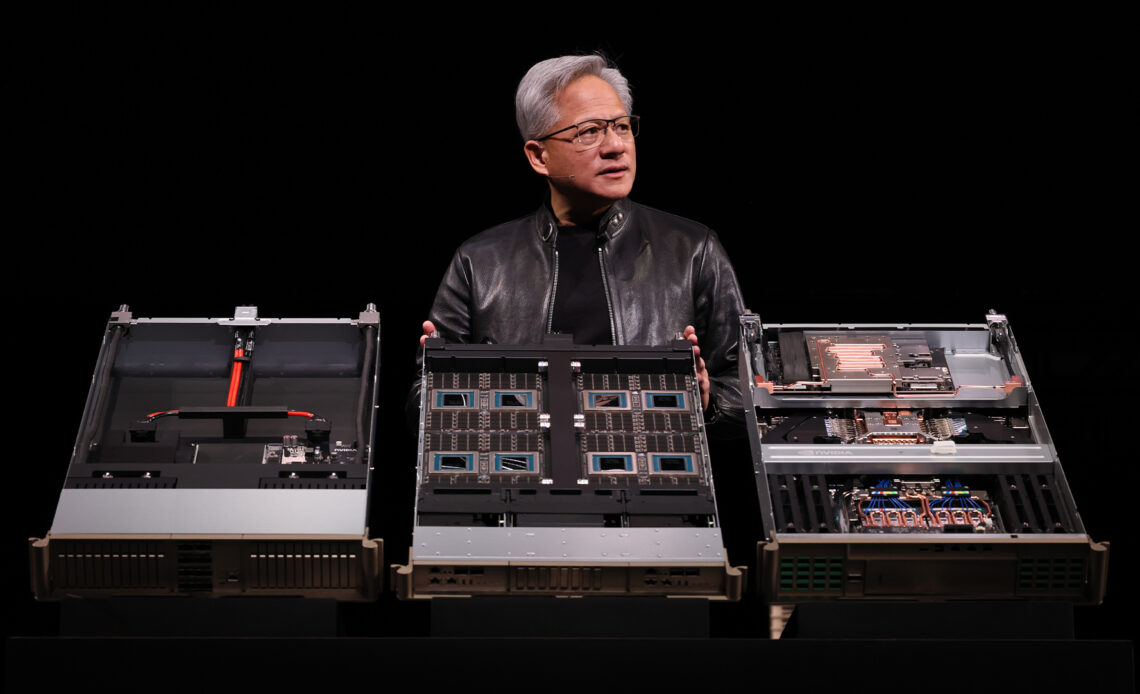
Nvidia’s latest decline follows reports that its board was considering removing Jensen Huang, the co-founder who has led the company since 1993.
The Wall Street Journal reported on November 11 that Nvidia’s directors were preparing to discuss Huang’s future following reports involving two extramarital relationships. Reuters relayed the report but said it could not independently verify it at the time.
One report concerned an alleged relationship with a company executive who reported to Huang.
Another concerned a Chinese businesswoman suspected of having intelligence connections.
The allegations have raised governance and national-security concerns, although no finding establishing that Huang compromised company secrets has been announced.
Nvidia had previously expressed confidence in Huang and his leadership team. His removal had not been publicly confirmed at the time of writing.
The uncertainty matters because Huang has been instrumental in Nvidia’s rise from a graphics-chip manufacturer into one of the world’s most valuable technology companies.
His potential departure would raise questions about succession, Nvidia’s relationships with major customers and its ability to maintain its lead in AI computing.
The stock has also suffered from broader investor concerns about AI spending, meaning the leadership controversy is not the only factor behind the decline.
Nvidia shares are trading at their cheapest valuation in years
Perhaps the strongest argument for buying Nvidia after the sell-off is its increasingly attractive valuation.
Nvidia was trading at approximately 11.4 times expected earnings over the next 12 months on November 11, compared with around 30.4 times for Advanced Micro Devices and 16.5 times for Broadcom.
Dow Jones Market Data separately reported that Nvidia’s forward price-to-earnings ratio had fallen to 11.66 on November 10, its lowest level since October 2011.
That represents a substantial change in how investors are valuing one of the biggest beneficiaries of the AI boom.
The decline has also created a sizeable gap between Nvidia’s share price and Wall Street’s existing forecasts.
Reuters reported that 59 of 64 brokerages covering Nvidia still rated the stock a buy or strong buy, with a median price target of $314.
However, those targets should be treated cautiously. Some may not fully reflect the latest leadership developments, and analyst forecasts are not guarantees of future returns.
The cheaper valuation also depends on Nvidia delivering the strong earnings growth currently expected. If those forecasts deteriorate, the apparent discount could quickly become less attractive.
Nvidia’s AI business remains a powerful reason to consider buying
Despite the turbulence surrounding its leadership, Nvidia’s latest financial results demonstrate the scale of demand for its AI technology.
The company reported second-quarter fiscal 2027 revenue of $96.2 billion, representing growth of 106% from the previous year.
Its data centre business generated approximately $89 billion in revenue, up 117% year-on-year, highlighting the continued investment in AI infrastructure.
Nvidia also reported a non-GAAP gross margin of 75%, indicating that its rapid revenue expansion has not come at the expense of profitability.
Importantly, the company forecast third-quarter revenue of approximately $108 billion, plus or minus 2%.
These figures suggest that Nvidia’s underlying business remains exceptionally strong, even as the share price comes under pressure.
Major cloud providers, AI developers and enterprises continue investing in computing infrastructure, while Nvidia’s hardware, software and networking ecosystem remains difficult for competitors to replicate.
For investors with a longer time horizon, the question is whether these competitive advantages can survive the potential departure of Huang.
Wall Street is becoming more cautious on Nvidia
While Nvidia’s financial performance remains impressive, several investment banks have become more cautious about the company’s outlook.
Baird downgraded Nvidia to neutral on November 11, citing uncertainty surrounding leadership and visibility into future data centre spending.
Morgan Stanley also removed Nvidia from its Top Pick list, although it maintained an overweight rating.
The downgrades highlight a broader concern: even if demand for AI chips remains strong today, investors may be overestimating how quickly the market can continue expanding.
Nvidia faces growing competition from AMD, custom AI processors developed by major technology companies, and changing customer spending priorities.
Meanwhile, restrictions on semiconductor exports to China remain a significant risk.
These challenges could become more difficult to navigate if Nvidia undergoes an unexpected leadership transition.
Should investors buy Nvidia before November 17 earnings?
Nvidia’s upcoming earnings announcement could be the next major catalyst for its share price.
The company is scheduled to report its third-quarter fiscal 2027 results on Tuesday, November 17, followed by a conference call at 5 p.m. Eastern Time.
Investors will be watching whether Nvidia can deliver against its approximately $108 billion revenue forecast, maintain its strong margins, and provide encouraging guidance for the following quarter.
Management commentary on AI infrastructure spending and customer demand will be particularly important.
Stronger-than-expected results could help restore confidence in Nvidia’s growth prospects, especially if the company also provides clarity over its leadership.
However, disappointing guidance or further uncertainty surrounding Huang could intensify the sell-off.
That creates two distinct approaches for investors.
Those with a long-term investment horizon may view the recent decline as an opportunity to accumulate Nvidia shares gradually, accepting that volatility could continue.
Investors focused on short-term returns may prefer to wait for the earnings report and a clearer indication of the company’s leadership plans before taking a position.
The verdict: Is Nvidia stock a buy right now?
Nvidia’s investment case has become more complicated, but the underlying business remains remarkably strong.
Revenue is growing at triple-digit rates, demand for AI infrastructure remains substantial, and the recent sell-off has pushed the stock towards historically low forward valuation multiples.
That combination makes Nvidia worth watching for investors seeking long-term exposure to artificial intelligence.
However, the possibility of a leadership change introduces risks that cannot be assessed through earnings multiples alone.
The sell-off may ultimately prove to be a buying opportunity, but Nvidia has become cheaper, not necessarily safer.
With earnings due on November 17 and the board’s next moves still uncertain, investors have clear reasons either to consider the lower valuation or to wait for further developments.
AI disclosure: AI tools assisted with research and drafting of this piece. An Invezz editor reviewed the facts, sources and wording before publication. Any opinions or analysis are Invezz’s, not those of an automated system.
The post Is Nvidia still a good buy after the stock sell-off? appeared first on Invezz