Tesla will report its third-quarter results after the US market closes on Wednesday, with investors looking for evidence that the electric-vehicle maker can protect profitability while spending billions of dollars to expand into artificial intelligence, autonomous driving and robotics.
The results come as the company faces pressure to sustain growth in its core automotive business while convincing investors that its longer-term ambitions can generate meaningful returns.
Speculation about a potential merger with Elon Musk’s SpaceX has added another dimension to the outlook after the billionaire said a combination would be “a good idea”.
Analysts expect Tesla to report revenue of $28.3 billion and earnings of 45 cents per share, compared with earnings of 50 cents per share on revenue of around $28.1 billion a year earlier.
Earnings before interest, taxes, depreciation and amortisation are expected to reach $3.7 billion, down 10% year on year.
Tesla has already reported third-quarter deliveries of 486,532 vehicles, beating expectations but declining 2.1% from the same period last year.
Tesla shares have fallen about 15% this year.
Options markets are pricing in a move of around 5.9% in either direction following the results, below the stock’s normal implied volatility.
Margins and capital spending under scrutiny
A key question for investors is whether Tesla can protect its margins, particularly without relying on regulatory credits earned by selling emissions allowances.
The company has missed analysts’ earnings estimates for four consecutive quarters, according to Louis Navellier, founder and chief investment officer of Navellier & Associates, who attributed the shortfall to operating margin compression and the ramp-up of Optimus robots.
Expert View
As a result, it is imperative that Tesla provide upbeat guidance regarding sales, operating margins, and signal when it expects Optimus robots to be profitable. I suspect that the Optimus details will remain a mystery, so do not be surprised if Tesla consolidates in the upcoming days, even if it provides upbeat guidance.
Capital expenditure is likely to be another major focus.
Analyst estimates compiled by Bloomberg indicate Tesla’s spending could exceed $25 billion in 2026, making this potentially its most expensive year on record as it invests in infrastructure and new businesses.
The company also took out $30 billion worth of credit and loan facilities last month.
Capital expenditures “will grow for the next two or three years,” Tesla Chief Financial Officer Vaibhav Taneja told investors earlier this year, citing investments in robotaxis, humanoid robots and other projects.
The spending outlook will matter because investors need to assess whether Tesla can finance its expansion while maintaining sufficient cash generation.
Cybercab expansion and Optimus timeline in focus
Beyond vehicle sales, investors will be looking for updates on Tesla’s efforts to transform itself into an AI and robotics company, with autonomous taxis, humanoid robots and energy storage expected to play increasingly important roles.
“The electric-vehicle maker increasingly wants to become an AI and robotics company, with robotaxis, humanoid robots and energy storage playing bigger roles,” Ruben Dalfovo, investment strategist at Saxo, wrote.
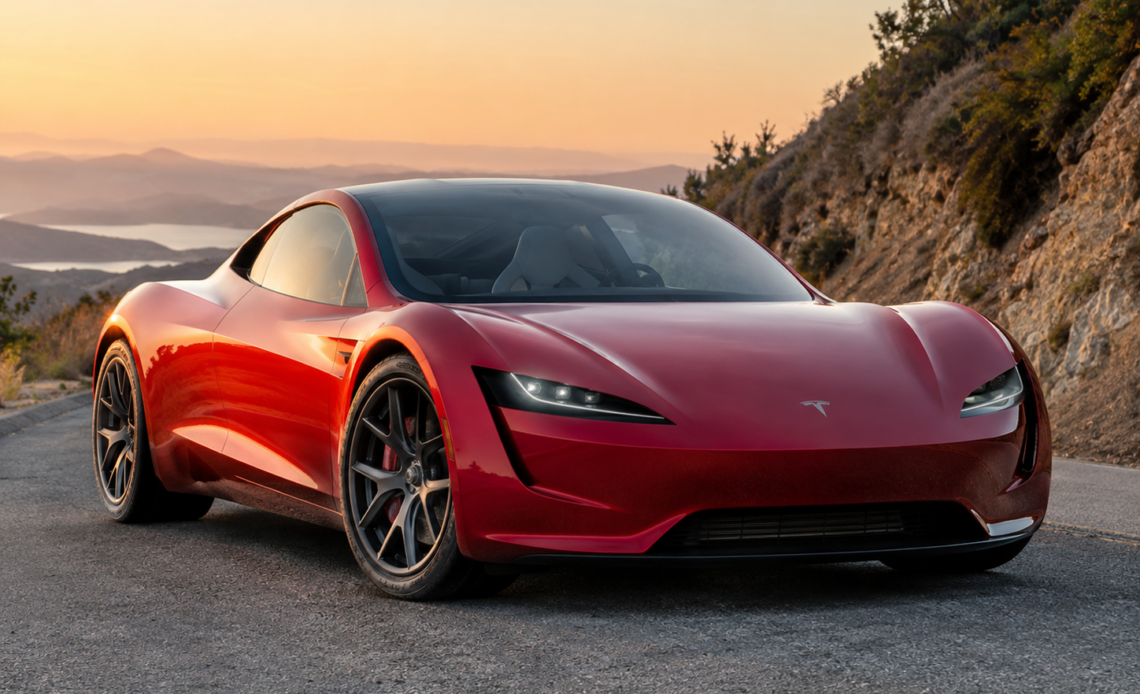
“Its recent Roadster unveiling demonstrated impressive engineering, but the more important developments concern Cybercab, Tesla’s purpose-built autonomous taxi, and Optimus, its humanoid robot,” he said.
Tesla began deploying its Cybercab robotaxis on its ride-hailing service in Austin, Texas, last month.
The autonomous vehicles could eventually improve profitability by allowing Tesla to generate revenue from transportation services, although their rollout remains limited amid a federal investigation.
Tesla has registered nearly 350 Cybercabs with the Texas Department of Motor Vehicles. According to the crowdsourced website RobotaxiTracker, 187 Cybercabs are active in Austin, representing about half of Tesla’s fleet in the city.
The company had only a few dozen vehicles available when the service began last month.
“The next test is whether TSLA can expand unsupervised service while maintaining performance as the fleet grows,” Oppenheimer analysts led by Colin Rusch wrote in a recent note to clients.
Investors will also seek clarity on the timeline for Optimus, Tesla’s humanoid robot project, and when it could become commercially profitable.
Energy storage offers another growth avenue
Tesla’s energy business could provide an additional source of growth as electricity demand increases and investment in energy infrastructure expands.
The company deployed 13.7 gigawatt-hours of batteries during the third quarter, supporting an established business that could help diversify revenue beyond vehicle sales, Saxo said.
However, Tesla’s broader ambitions require substantial investment before their financial benefits become clear.
Investors will be watching whether spending on autonomous driving, robotics and infrastructure translates into sustainable earnings growth, rather than adding further pressure to cash flow.
Musk adds fuel to Tesla-SpaceX merger speculation
The earnings report also comes as speculation about a potential merger between Tesla and SpaceX intensifies.
Musk said on Tuesday that combining the two companies would be “a good idea” and that special committees had been formed to discuss a possible union.
SpaceX shares rose 8% in extended trading following the remarks, while Tesla rose over 2% during premarket trading on Wednesday.
A merger could bring together Tesla’s vehicle manufacturing, energy storage, autonomous driving and robotics operations with SpaceX’s Starlink broadband network, launch services and future space ventures.
The combined company could be worth around $3.5 trillion, placing it among the world’s largest companies.
Supporters argue that a deal could allow capital to be allocated more efficiently across businesses with increasingly overlapping technological ambitions.
Critics, however, warn that investors could be exposed to a broader range of technical, regulatory and execution risks across businesses with different financial requirements.
Gene Munster, managing partner at Tesla investor Deepwater Asset Management, said the prospect of a deal had become more likely.
Going into this, I’d have said there’s a 90% chance that something happens in the next two years. It’s a 95% chance, I think, now. It might even be in the next year. But clearly there is momentum around this internally and I think that ultimately it does happen.
Dan Ives, partner and senior managing director at Yorkville Ives & Co, also backed a potential combination, while highlighting the importance of the terms offered to shareholders.
“We believe this is a no-brainer move for both SpaceX and Tesla, it comes down to the price for shareholders. The price for Tesla shares would have to be likely in the $550 range to get done and approved. Shareholders would want this marriage, it makes a ton of strategic sense.”
The post Tesla earnings: margins, Cybercab, Optimus in focus as SpaceX merger talks intensify appeared first on Invezz